Table of Contents
If you’re an investor actively building a portfolio, then you have a form of wealth balance in mind. You build your core holdings, check your balances, and suddenly wonder if you are missing something vital. Do you strictly need property in the mix?
Well, it absolutely depends. REITs (Real Estate Investment Trusts) can certainly add vital listed real estate exposure. Plus, they offer a completely different income profile compared to standard tech or banking stocks. Yields often look incredibly attractive.
But their actual mathematical benefit relies heavily on your existing holdings. It also hinges on the specific type of trust, current market valuations, and your personal tax context. REITs are absolutely not a mandatory requirement for every single investor out there.
What a REIT Actually Owns and Pays
Real estate investment trusts are not all built the same. They generally fall into three completely distinct categories.
- Equity trusts are the most common. They physically buy, own, manage, and collect rent on real-world properties.
- Mortgage trusts, on the other hand, act more like specialized banks. They lend money to property owners or buy up existing mortgages, earning their keep on the interest rate spread.
- Hybrid structures exist that mix both physical ownership and lending.
How you access them matters just as much. You can buy listed versions that trade instantly on major stock exchanges. Non-traded versions are also registered with financial regulators but sit outside the public markets, meaning you cannot sell them on a Tuesday afternoon just because you want cash.
Private structures operate completely in the shadows, reserved exclusively for institutional or highly accredited investors. If you are an investor living in Spain or the broader EU, you will constantly hear the term SOCIMI.
These are the localized European equivalent. While global REITs and Spanish SOCIMIs share similar tax-advantaged goals and payout structures, they are distinctly different legal products.
Property Sectors and Sources of Concentration
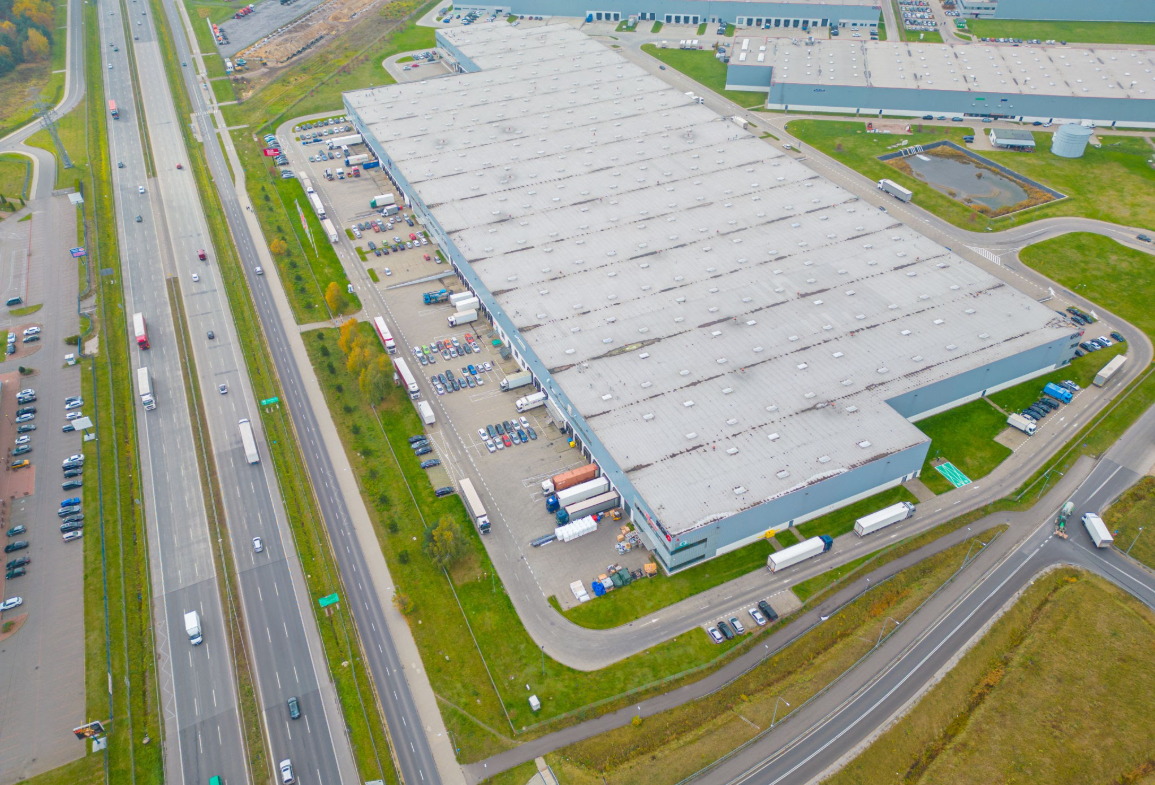
A large-scale logistics center is very different from a high-rise in the downtown area. An investor who chooses to invest in this asset class is making a wager on the particular economic sector. The traditional heavyweights are residential, office, retail and industrial properties.
However, the way the modern real estate market operates is quite different from how it was just a few years ago. Because of the dramatic shift, specialized logistics, specialized healthcare facilities, hospitality venues, and massive data-centre exposures dominate the total market cap today.
Two completely different REITs can respond to the exact same macroeconomic event in opposite ways. They do this because the fundamentals backing them are radically different. They also have different tenants with different needs.
While an apartment renter may sign a 12-month agreement, hospitals would often sign leases of up to 20 years. In addition, geography, local zoning laws, and underlying financing mechanics change the risk profile of the different property types completely.
How REITs May Add Diversification
Adding physical property to your financial accounts can radically shift your overall market exposure. Real estate usually dances to a different beat than pure software equities or corporate debt.
The relationship between public real estate and the overall stock market is not necessarily a 1-to-1 match historically. The correlation between public real estate and the S&P 500 over the last 33 years (historical Nareit data in USD) was approximately 0.74.
This is not a permanent, ironclad law of physics. Sometimes property stocks zig exactly when tech stocks zag. Other times, during massive liquidity crunches, everything crashes together.
This unique property-sector exposure and distinct, high-yield income stream is exactly how REIT diversification functions in theory. It introduces a cash-flowing physical asset into your digital holdings. If you use REITs correctly, they can certainly help you build a much more robust portfolio diversification strategy.
Why REITs Can Still Behave Like Equities
Make no mistake about the nature of public markets. When severe panic hits the stock exchange, listed property trusts feel the pain immediately.
They trade publicly on major global exchanges. Therefore, they are constantly subjected to daily market sentiment. Rapid algorithmic trading swings their prices by the second.
Heavy leverage sharply amplifies these wild market swings. Massive debt loads make their stock prices hypersensitive to macroeconomic fears. Sector concentration also means a sudden tech stock sell-off can drag down data-centre trusts simultaneously.
The listed wrapper itself changes the fundamental math. Public stock prices fluctuate wildly based on human emotion. Meanwhile, infrequently valued direct property appears artificially stable simply because it is not priced every single day.
The Main Risks to Review
Every single asset class carries inherent danger. REIT risks are highly specific. They require ruthless review before you ever buy a single share. Interest rates present the absolute most obvious threat.
Rising rates drastically increase corporate refinancing costs. They also make alternative, safer income investments look much more appealing to yield chasers.
Another set of REIT risks involves underlying operational factors. Dropping physical occupancy rates destroy revenue. Poor tenant quality and the broader economic property cycle directly impact cash flow.
Finally, you must review liquidity and payouts. Listed trusts offer high liquidity but highly volatile pricing. Non-traded versions effectively trap your cash for years. In both scenarios, distribution changes can happen overnight. A sudden dividend cut usually triggers a massive stock sell-off.
REITs, Direct Property and Real Estate Funds Compared
Buying physical brick-and-mortar buildings is radically different from buying liquid shares. Direct property requires massive upfront capital. It also demands immense, exhausting active management. Funds pool your money to handle this burden for you entirely.
Individual REITs vs REIT ETFs
Choosing your specific entry vehicle matters immensely for portfolio diversification. You can choose to invest in single companies or buy a massive, pre-packaged basket of them, called ETF.
Individual stock picking offers absolutely zero management fees. However, it brings massive concentration risk. A single corporate bankruptcy hits your portfolio incredibly hard.
Real estate ETFs intelligently spread that inherent risk out. They provide instant, massive market scale. You get extreme transparency. However, you will pay an ongoing expense ratio strictly for that convenience.
Do not assume a fund offers complete safety, though. A supposedly broad ETF might still be dangerously concentrated. It could be heavily skewed toward a single country. It might lean too hard on vulnerable retail shopping malls.
How to Read REIT Operating Metrics
Standard stock metrics completely fall short here. You need a highly specialized vocabulary to read these property financials correctly. Start with the absolute basics.
- Look closely at physical occupancy rates. Check the average tenant lease terms. Review their historical rent growth over the past decade.
- Next, you must verify their debt maturity schedules. It tells you how exposed the fund currently is to refinancing risk, liquidity crunches, and interest rate volatility.
- You also need to review the critical loan-to-value (LTV) ratio. The LTV gauges their survival odds during a severe credit crunch and flags potential insolvency risks if property market values decline.
- Look specifically for Funds from Operations (FFO). Forget standard earnings per share, the FFO tells you the true operating cash flow of a REIT.
- Review their Adjusted Funds from Operations (AFFO). These specialized metrics strip out paper depreciation to show the actual cash generated.
- Finally, compare the stock’s share price to its Net Asset Value (NAV). NAV gives you the picture of the true intrinsic market value of the company’s underlying physical properties and assets minus its liabilities.
Be warned, though. Definitions vary wildly between different management teams. Always pull these specific figures directly from a recently dated company report.
A Portfolio Overlap Scenario
Imagine you already heavily own a broad global index fund. It is massive and covers thousands of equities worldwide. That broad global equity fund almost certainly already owns major property companies.
You already have some base-level real estate exposure right now. If you then go out and haphazardly buy a separate property fund, you might just be needlessly duplicating your exact holdings.
However, a highly targeted property fund can deliberately shift your overall sector exposure. Let’s say your broad equity fund is extremely heavy on downtown office buildings.
You might consciously buy a specialized logistics trust to aggressively tilt your diversified portfolio toward e-commerce warehouses. This highly intentional tilting is a distinctly smart way to approach true REIT diversification.
Income Is Not the Same as Low Risk
High dividend yields can be a devastating trap. Do not blindly chase a massive payout. Distributions can, and frequently do, change rapidly. If a company suddenly struggles to keep tenants, the rent stops coming in. When the rent stops, the dividend gets slashed instantly.
Furthermore, a stated yield might mathematically rise simply because the underlying share price has completely collapsed. That is absolutely not a sign of financial health. It is a massive, glaring red flag.
You must carefully distinguish between the cash distribution you receive, the actual total return of the investment, and your personal tax outcome. Ignoring these complex REIT risks is a classic rookie mistake. Always aggressively analyze the total picture before buying REITs for the yield alone.
Questions for a Spain-Based Investor
Your geographic location dictates your available options. Spanish and EU investors face a highly unique regulatory landscape. First, rigorously check product availability and currency exposure.
Are you buying strictly in Euros, or are you accidentally taking on massive US Dollar currency risk? Next, you absolutely need to review the Key Information Document (KID). European financial regulations mandate this document for a very good reason.
- What is the specific withholding tax rate on the foreign dividend?
- Is your brokerage account structure optimally set up for this specific asset class?
- Are you actually buying a highly regulated SOCIMI, a global property trust, a UCITS ETF, or an opaque mutual fund?
The tax details are notoriously complex. Current Spanish tax guidance generally treats SOCIMI dividends as standard savings income, but foreign withholding taxes can severely complicate your actual net return. Understanding local tax implications is one of the more overlooked REIT risks. Always consult a local tax professional to thoroughly protect your diversified portfolio.
When REITs May Add Little Diversification
Sometimes, adding property to your financial accounts does absolutely nothing helpful for you. If you already physically own three rental houses in your city, buying property stocks just recklessly piles on existing property concentration.
If you own a massive broad market index, you might just be blindly creating overlapping funds. Extremely short investing horizons are also a massive problem. Property is inherently a long game.
Additionally, if the specific vehicle uses extreme high leverage, it behaves much more like a highly risky debt instrument than a stable, boring building. Finally, if your current lifestyle requires rock-solid, guaranteed income that absolutely cannot tolerate sudden dividend cuts, this volatile asset class might fail you completely.
REIT diversification is absolutely not a magic shield against market gravity. Always rigorously measure it against your wider portfolio diversification goals before deploying capital. If it doesn’t fit your diversified portfolio, do not force it. Buying REITs just because you feel you should is a terrible strategy.
Conclusion: REITs Can Diversify a Portfolio, but the Details Decide
Do REITs actually belong in a diversified portfolio? Yes, conditionally. They can act as an incredibly potent tool for portfolio diversification. They offer highly liquid, cheap access to massive, otherwise completely unreachable commercial assets.
But the granular details ultimately decide your fate. You must rigorously audit your existing property exposure first. You have to carefully pick the right vehicle type and the exact right economic sector. You must heavily scrutinize the hidden leverage involved and deeply question the actual income reliability.
Currency fluctuations and your highly localized tax context will ruthlessly shave points off your net return if ignored. There is no universal, one-size-fits-all allocation percentage. There is no simple, blanket yes-or-no recommendation here.
Managing REIT risks requires continuous diligence. Executing proper REIT diversification requires a customized, highly intentional strategy. Make absolutely sure it actually serves the long-term goals of your specific, carefully planned diversified portfolio.
Disclaimer: The content provided in this article is for educational and informational purposes only and should not be considered financial or investment advice. Interacting with blockchain, crypto assets, and Web3 applications involves risks, including the potential loss of funds. Venga encourages readers to conduct thorough research and understand the risks before engaging with any crypto assets or blockchain technologies. For more details, please refer to our terms of service.